Introduction
Credit plays a crucial role in modern financial life. Whether you’re applying for a loan, renting an apartment, or even landing a job, your credit can significantly influence the opportunities available to you. Understanding how credit works and how to manage it effectively is essential for long-term financial health.
What Is Credit?
Credit is the ability to borrow money or access goods and services with the agreement that you will pay later. Lenders evaluate your borrowing history and financial behavior before deciding whether to extend credit to you.
Key Components of Credit
- Creditworthiness: A lender’s assessment of your ability to repay.
- Credit Score: A numerical indicator of your credit risk.
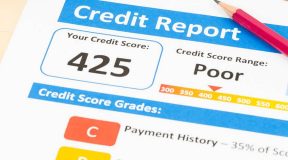
- Credit Report: A detailed record of your credit accounts and payment history.
Types of Credit
1. Revolving Credit
This type allows you to borrow repeatedly up to a fixed limit.
Examples include:
- Credit Cards
- Lines of Credit
Benefits: Flexible spending, builds credit when used responsibly.
Risk: High interest rates if balances are carried month to month.
2. Installment Credit
You borrow a set amount and repay it in fixed installments.
Common forms:
- Auto Loans
- Personal Loans
- Student Loans
- Mortgages
Benefits: Predictable payments, often lower interest rates.
Risk: Missed payments can severely affect credit.
3. Open Credit
You must pay the full balance each period.
Examples include:
- Utility Bills
- Charge Cards
Understanding Credit Scores
A credit score summarizes your credit history into a single number. Most lenders rely on this score to gauge financial responsibility.
Factors That Affect Your Credit Score
- Payment History (Most Important): On-time payments boost your score.
- Credit Utilization: Using too much of your available credit lowers your score.
- Length of Credit History: Longer history equals more reliability.
- New Credit Inquiries: Too many applications can negatively affect your score.
- Credit Mix: A combination of different credit types is beneficial.
Why Credit Scores Matter
A strong score helps you secure better financial opportunities, such as:
- Lower interest rates
- Higher credit limits
- Easier loan approvals
- Favorable insurance premiums
How to Build Good Credit
Start with Responsible Habits
- Always pay bills on time
- Keep credit utilization low (ideally under 30%)
- Monitor your credit reports regularly
- Avoid frequent credit applications
- Maintain long-standing accounts
Smart Credit Strategies
- Use a secured credit card if you’re new to credit.
- Become an authorized user on a family member’s card.
- Make small purchases and pay them off monthly.
Common Credit Mistakes to Avoid
- Maxing out credit cards
- Ignoring bills or paying late
- Closing old accounts prematurely
- Responding to every credit offer
- Failing to check your credit report for errors
How to Repair Damaged Credit
Practical Steps
- Dispute inaccuracies on your credit report
- Set up automatic payments to avoid missed due dates
- Pay down high balances aggressively
- Negotiate with creditors for better payment terms
- Consider credit counseling for complex issues
Why Credit Matters in Everyday Life
Credit influences far more than just loans. It can impact:
- Renting a home
- Securing lower insurance rates
- Employment applications in certain industries
- Utility deposits
- Approval for mobile phone plans
Frequently Asked Questions (FAQ)
1. How long does it take to build good credit from scratch?
It typically takes three to six months of responsible use to begin generating a score and up to a year or more to achieve a strong rating.
2. Does checking my own credit score lower it?
No. Personal credit checks are considered soft inquiries and do not impact your score.
3. Can closing a credit card hurt my credit score?
Yes. Closing a card can reduce your available credit and shorten your credit history, both of which may lower your score.
4. How often should I review my credit report?
Reviewing your reports at least once a year is recommended to catch errors or suspicious activity early.
5. What happens if I miss a payment?
A late payment can stay on your credit report for up to seven years and significantly harm your score, especially if it’s more than 30 days late.
6. Does having multiple credit cards hurt credit?
Not necessarily. Multiple cards can help maintain low utilization, but mismanagement or overspending can negatively affect your score.
7. How can I quickly improve my credit score?
Paying down existing balances and ensuring all bills are paid on time are two of the fastest ways to see improvement.
If you’d like, I can also create a downloadable PDF version of this article.